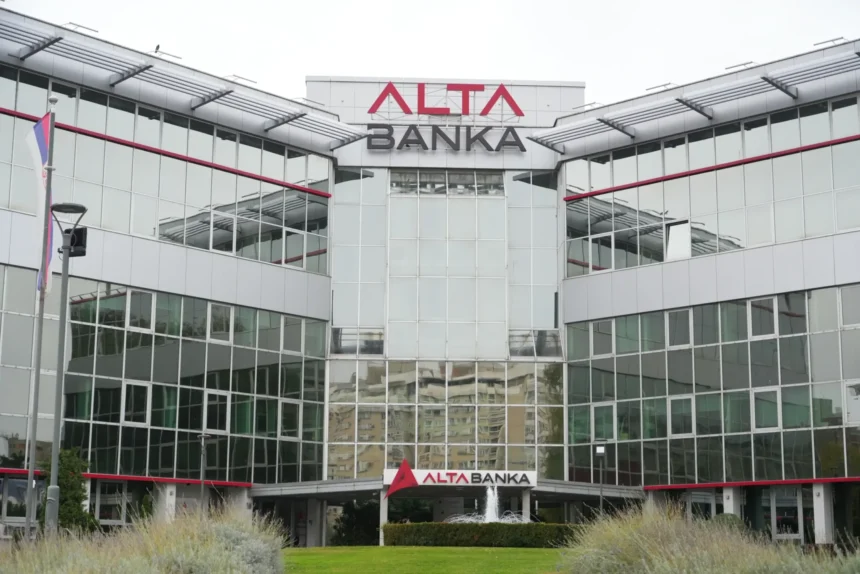
Questions are mounting over the handling of Alta Bank’s collapse in Serbia, with concerns that the bankruptcy proceedings could make it increasingly difficult to establish where hundreds of millions of euros went, who withdrew the money and whether financial regulators helped facilitate or conceal the transfers.
In an analysis published on November 11, lawyer Veljko Grković, Belgrade Faculty of Philosophy professor Ognjen Radonjić, and Faculty of Organisational Sciences professor Vladimir Obradović argue that Serbia’s National Bank (NBS) had sufficient information, authority and time to intervene but failed to prevent the outflow of funds.
They warn that unless crucial financial and electronic records are immediately secured, the bankruptcy process could effectively obstruct investigations into suspicious transactions and potential money laundering.
The NBS revoked Alta Bank’s operating licence on October 30, three days after publicly dismissing warnings that money was being rapidly transferred out of the institution. According to the authors, the bank’s deposits fell by at least 16.6 billion dinars during October 28 and 29 alone.
The developments have raised questions about the central bank’s public statements and the timing of its intervention.
According to information from the NBS decision made public, Alta Bank reportedly held 59.97 billion dinars in cash in its vaults as of September 30. This represented 221.57 percent of its regulatory capital, compared with a banking-sector average of 29.47 percent.
The central bank itself reportedly assessed that the bank could lose more than its entire regulatory capital in the event of theft, fraud or a fire in its vault.
At the same time, Alta Bank was paying depositors interest rates almost twice the industry average, at 3.13 percent compared with 1.59 percent. Deposits from the public sector and state-owned enterprises, which accounted for a quarter of the bank’s total deposits, reportedly carried interest rates of up to 5.61 percent.
The authors question why the bank was attracting expensive deposits while allegedly keeping such substantial amounts of cash in its vaults rather than using the funds to generate returns.
Questions over what the NBS leadership knew
Concerns about Alta Bank’s liquidity reportedly existed as early as February 2026, when shortages in funds needed to meet maturing obligations had already been recorded.
Despite these warning signs, the authors argue that inspections were conducted primarily on the basis of reports submitted by the bank itself.
Only on October 29 did the NBS instruct Alta Bank to conduct its own cash count within three working days. The following day, the institution lost its operating licence.
Lawyer Ivan Ninić had previously announced that he had requested an urgent extraordinary inspection of a bank that had allegedly begun transferring money rapidly to accounts in Moscow and Skopje from October 26.
On October 27, the NBS responded that the transfers were being conducted through regular payment channels and warned against spreading unverified claims that could cause unnecessary public concern.
However, the subsequent reduction of at least 16.6 billion dinars in deposits over two days intensified questions about the central bank’s response.
Following the licence revocation, NBS deputy governors acknowledged that the bank’s actual situation had differed dramatically from the information contained in its reports.
The central bank also suggested that determining whether the reported cash reserves actually existed was a matter for the police and prosecutors.
The authors argue that this raises serious questions about why the NBS publicly reassured depositors on October 27 despite apparently lacking verified information about the bank’s actual financial position.
They insist that Governor Jorgovanka Tabaković should not merely be questioned as a witness but that her own decisions and potential responsibility must also be examined.
According to the authors, investigators should establish whether the central bank leadership’s actions or deliberate inaction enabled or concealed the withdrawal of funds.
They also stress that responsibility cannot be limited to the regulator. Members of Alta Bank’s executive and supervisory boards must be investigated to determine what they knew about the bank’s cash reserves and suspicious financial movements, as well as whether they took decisions that facilitated or failed to prevent potential irregularities.
Bankruptcy could complicate investigations
The Commercial Court in Belgrade opened bankruptcy proceedings against Alta Bank on November 3, appointing the Deposit Insurance Agency as bankruptcy administrator.
The authors warn that bankruptcy proceedings primarily aim to settle creditors’ claims and liquidate assets, rather than investigate possible money laundering or establish criminal responsibility.
The Deposit Insurance Agency has been instructed to inventory the bank’s assets and prepare an initial bankruptcy balance sheet within 60 days, including information about significant transactions conducted during the six months preceding the opening of bankruptcy proceedings.
However, the authors argue that this timeframe is insufficient to uncover potentially complex financial schemes that may have operated over several years.
They also warn that the departure of bank employees familiar with its internal systems, transaction records and anti-money laundering procedures could make it significantly harder for investigators to reconstruct the movement of funds.
Documents may technically remain preserved, but without proper organisation and access to the employees who understand them, identifying suspicious transactions and linking them to their beneficiaries could become extremely difficult.
Questions about possible money laundering
The authors are calling for an examination of whether Alta Bank reported suspicious transactions to Serbia’s Administration for the Prevention of Money Laundering and whether the NBS properly monitored the bank’s compliance with anti-money laundering regulations.
Banks are required to maintain detailed information about their customers, beneficial owners, the economic purpose of transactions, non-resident accounts and international payments.
The authors argue that examining individual companies or transfers separately would be insufficient. Investigators must analyse the bank’s overall transaction network to identify patterns that might otherwise remain undetected.
They also question whether Alta Bank properly applied the indicators used to identify potential money laundering and whether suspicious transactions were reported to the relevant authorities.
Six urgent measures proposed to preserve evidence
To prevent the loss of evidence, the authors propose a series of immediate measures involving the NBS, the Deposit Insurance Agency, the Administration for the Prevention of Money Laundering and the competent prosecution authorities.
Their recommendations include:
- Creating a complete forensic copy of the bank’s electronic records, including its core banking system, SWIFT messages, anti-money laundering software, generated alerts, emails and system access logs, while maintaining a documented chain of custody.
- Preserving all customer files, including know-your-customer documentation, risk assessments, beneficial ownership records, internal anti-money laundering reports and communications with the relevant authorities.
- Ensuring that records are organised to allow investigators to examine all accounts and transactions throughout the bank’s entire operating history, rather than focusing exclusively on the six months preceding bankruptcy.
- Prioritising non-resident accounts, large international transfers, unusual transactions and payments displaying indicators of potential money laundering that may not have been reported.
- Prohibiting the destruction, disposal or sale of IT equipment and data storage devices until the investigation has been completed.
- Establishing a formal protocol between the Deposit Insurance Agency, the NBS, the money laundering prevention administration and prosecutors to guarantee access to relevant information, potentially with the assistance of an independent forensic audit.
They also insist that employees familiar with the bank’s systems and archives should be retained to ensure that investigators can obtain the necessary documentation without delay.
Investigation must establish where hundreds of millions went
The authors stress that Alta Bank’s collapse is not simply a question of compensating depositors through Serbia’s deposit insurance system.
The central issue, they argue, is whether money potentially obtained through corruption or other criminal activities entered legitimate financial channels, who participated in those transactions and where hundreds of millions of euros ultimately went.
They maintain that investigators must establish why the NBS failed to intervene earlier, what information was available to the central bank and Alta Bank’s management, and whether decisions or deliberate failures to act enabled the withdrawal of funds.
The authors conclude that neither the bank’s management nor the central bank should be allowed to avoid scrutiny by shifting responsibility onto one another.
They warn that bankruptcy must not become a shield for those responsible at Alta Bank or within the NBS, and that preserving the evidence immediately is essential to ensuring that the full circumstances surrounding the bank’s collapse are eventually established.